 Symbolbild · KI-generiert
Cash Runway, Burn Rate & Technology: Three Benchmarks for Quantum Pure-Plays
The Quantum Field After the Hype: What Remains?
Quantum computing stocks have taken investors on an emotional roller coaster over the past two years. After a spectacular rally that temporarily pushed some pure-plays into valuation territory far beyond their current revenue levels, an equally abrupt correction followed. The pattern is classic for early-stage technology segments: the market first prices in the vision, then comes disillusionment — and finally, selection. Who survives?
Three publicly listed companies currently dominate the conversation: Rigetti Computing (Nasdaq: RGTI), D-Wave Quantum (NYSE: QBTS), and IonQ (NYSE: IONQ). All three are considered pure quantum plays — so-called pure-plays — all three are not yet profitable, and all three are pursuing technologically distinct paths. For newcomers to the topic, it is essential to understand: technology alone does not support an investment decision. Three additional benchmarks are required.
Superconducting, Annealing, Ion Trap: What Sets the Technology Paths Apart
The first step is understanding the fundamental differences — not to crown a winner, but to categorize the risk profile of each approach.
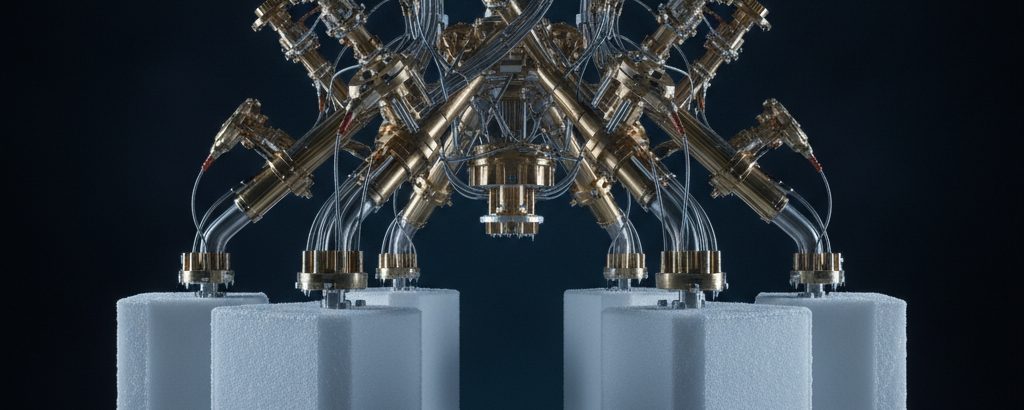
Rigetti Computing relies on superconducting qubits. These must be cooled to temperatures near absolute zero — hence the characteristic cooling "chandelier" structures often seen in laboratory images. The advantage: high scalability in theory. The disadvantage: extreme technical demands on hardware and error correction that have so far limited commercial use.
D-Wave Quantum takes a different route — quantum annealing. Rather than universal quantum computation, D-Wave specializes in optimization problems: logistics planning, portfolio optimization, materials design. This is a narrower application field, but a more mature product. D-Wave actually has paying customers and offers cloud access to its systems — a circumstance that distinguishes its revenue profile from that of its competitors.
IonQ, by contrast, works with trapped-ion technology. Individual ions are captured in an electromagnetic field and used as qubits. Trapped ions are considered stable and fault-tolerant, but are harder to scale than superconducting systems. IonQ has announced partnerships with cloud providers and has secured government contracts in the United States.
| Company | Technology Approach | Strength | Monetization Stage |
|---|---|---|---|
| Rigetti (RGTI) | Superconducting Qubits | Scaling potential | Early stage, primarily R&D contracts |
| D-Wave (QBTS) | Quantum Annealing | Maturity, customer base | Commercial cloud access |
| IonQ (IONQ) | Trapped Ions | Fault tolerance | Cloud + government contracts |
Burn Rate and Cash Runway: The Real Survival Question
All well and good — but technological differentiation alone says nothing about whether a company can financially bridge the gap to commercial viability. This is where the three structural metrics that matter most to small-cap investors come into play.
1. Cash Runway: This is calculated by dividing the cash balance by the monthly burn rate (net cash outflow). A company with $80 million in cash and a monthly burn rate of $10 million has a calculated runway of eight months — and must either raise new capital or drastically cut spending. All three companies mentioned are still far from profitability. Investors should consult the latest quarterly figures from published company reports to calculate the respective runways.
2. Capital Increase Risk (Dilution): Once the runway grows short, many pre-profit companies resort to a capital increase — issuing new shares to raise fresh funds. This dilutes the stake of existing shareholders. In the quantum segment, this pattern is not the exception but the rule: all three pure-plays have relied on equity financing in the past. The lower the share price at the time of such a move, the greater the dilution effect.
3. Customer Pipeline and Path to Monetization: Announcements of partnerships or pilot projects are not revenue. What matters is whether a company can demonstrate recurring income — for example, through subscriptions for cloud access to quantum computers (Annual Recurring Revenue, ARR) or through framework agreements with callable order volumes. A press release about a "strategic collaboration" with no concrete contract value is a weak signal; a multi-year government contract with fixed call-offs is structurally far more valuable.
Valuation in Narrative Mode: Why Share Prices Fluctuate So Sharply
Anyone who wants to understand the sharp price movements of quantum pure-plays must grasp one market phenomenon: in the early stage of a technology sector — long before profits exist — market capitalization is determined almost exclusively by narrative. This means that a report of a new qubit record, a government initiative for quantum research, or a prominent partner name can move the share price dramatically in the short term, without the company's fundamental situation having changed at all.
This phenomenon can be compared to the dot-com era: back then, the mere mention of "Internet" in corporate reports drove prices higher. Later, when the profitability question became unavoidable, brutal selection followed. Of the hundreds of publicly listed internet companies around the year 2000, only a few survived — including those with a genuine customer base, controllable capital deployment, and a scalable business model.
In the quantum segment, the analogy is not perfect, but instructive. Unlike pure software companies, quantum firms struggle with extreme hardware and infrastructure costs. Every advance in error correction or qubit count requires intensive laboratory development — and thus ongoing expenditure that shortens the runway.
What Structurally Different Approaches Mean for Investors
From an analytical perspective, it can be noted: D-Wave's more mature approach with paying customers and a tighter niche positioning offers a different risk structure than the broader but earlier-stage platform ambitions of Rigetti or IonQ. This does not mean that D-Wave is the "better" investment — but it illustrates how different the monetization paths are and why a blanket comparison of share prices reveals little.
IonQ, in turn, has tapped into a revenue stream through government contracts — for example within the framework of U.S. defense programs — that is less dependent on public capital market access than pure commercial customer contracts. Such contracts can extend the runway, but are themselves tied to political priorities and budget cycles.
Rigetti faces the challenge of converting its technological progress in superconducting systems into commercial contracts quickly enough before capital runs out. The question here is not only technical but entrepreneurial: can management successfully turn pilot projects into firm order intake?
For investors monitoring this segment, a structured approach is advisable: review quarterly reports for burn rate and cash balance, distinguish between press releases and firm order intake, and do not treat share price movements alone as an indicator of fundamental progress. The risk of total loss of capital is real in a segment without profits and with high fixed costs — even if the technology holds long-term transformative potential.
Key Terms for Getting Started in the Quantum Segment
- Cash Runway
- The period a company can sustain operations with its current liquid assets at a constant rate of spending. Calculation: cash balance ÷ monthly burn rate. The shorter the runway, the more urgent the next funding round.
- Burn Rate
- A company's monthly net cash outflow when it has not yet generated positive operating cash flows. High burn rates are common in capital-intensive technology segments such as quantum computing, but increase pressure on management.
- Dilution
- When a company issues new shares to raise capital, the percentage stake of existing shareholders in the company decreases. For pre-profit companies, dilution is a recurring risk.
- Pure-Play
- A company that operates exclusively within a single technology segment — here: quantum computing. This increases both the chance of outsized growth and the risk of failure.
- ARR (Annual Recurring Revenue)
- Annually recurring revenue, for example from cloud subscriptions. For quantum companies, an important indicator of customer base stability — more meaningful than one-time project contracts.
- Quantum Annealing
- A specialized quantum approach for solving optimization problems, pursued by D-Wave. Not a universal quantum computer, but commercially deployable earlier than gate-based systems.
- Trapped Ion
- A quantum technology in which individual ions are held as qubits in an electromagnetic field. Considered particularly fault-tolerant, but harder to scale than superconducting systems.
- Total Loss of Capital
- Complete loss of the capital invested. For speculative small caps without profits, this scenario is possible — for example, if capital is exhausted and no further financing is secured. This article is not a substitute for professional investment advice.
⚠️ Important notice: This article is for informational and educational purposes only. It does not constitute investment advice, a recommendation, or a solicitation to buy or sell any security. Investments in small-cap exploration and mining companies carry a high risk, including the potential total loss of capital. Before making any investment decision, consult a registered financial advisor and conduct your own analysis. Aktienatlas-Redaktion is not responsible for decisions taken based on the content published here.
Educational content only, not investment advice. Small caps are highly speculative and total loss is possible.